When the Numbers Stop Making Sense
Your business is "profitable" on paper, but your bank account says you're broke. That isn’t just a bad week—it is the classic "Profit vs. Cash Flow" trap. Most founders confuse accounting wins with real money, and that mistake kills more startups than a bad product ever could. You don't need more sales; you need to change how you manage the cash you already have. Let’s look at why you’re drowning and how to fix it immediately.
That night, I realized I had been staring at the wrong numbers the whole time. I was obsessed with "profit," but I was completely ignoring "cash flow." It felt like drowning while standing in a shallow pool. I had done the work, but the money hadn't arrived, and the bills were already due.
The stress wasn't just about the money; it was the sheer confusion. My friends thought I was successful because I was "busy," but I felt like a failure because I was constantly scraping by. My sleep vanished, my relationships suffered, and every time the phone rang, I feared it was a creditor or an angry vendor.
The Founder’s Cheat Sheet: Quick Wins
Before you read on, keep these 4 rules top of mind:
- Cash is King: You can survive a month without profit, but you cannot survive a day without cash.
- Don't Finance Clients: Move to "Due on Receipt" terms immediately. Stop acting like a bank.
- Separate Everything: Your personal and business bank accounts must never touch. Period.
- The Weekly Ritual: Spend 60 minutes every Friday auditing your expenses. If it isn't making money, cut it.
The Great Misunderstanding: Profit vs. Reality
Many new business owners fall into the trap of thinking profit equals cash. It is a dangerous lie. You can be profitable on your accounting software but completely insolvent in your bank account.
This happens because of the gap between when you earn money and when you actually collect it. If you sell a product today but the customer doesn't pay for sixty days, you are essentially providing a loan to that customer. Meanwhile, your rent, electricity, and software subscriptions are due today, not sixty days from now.
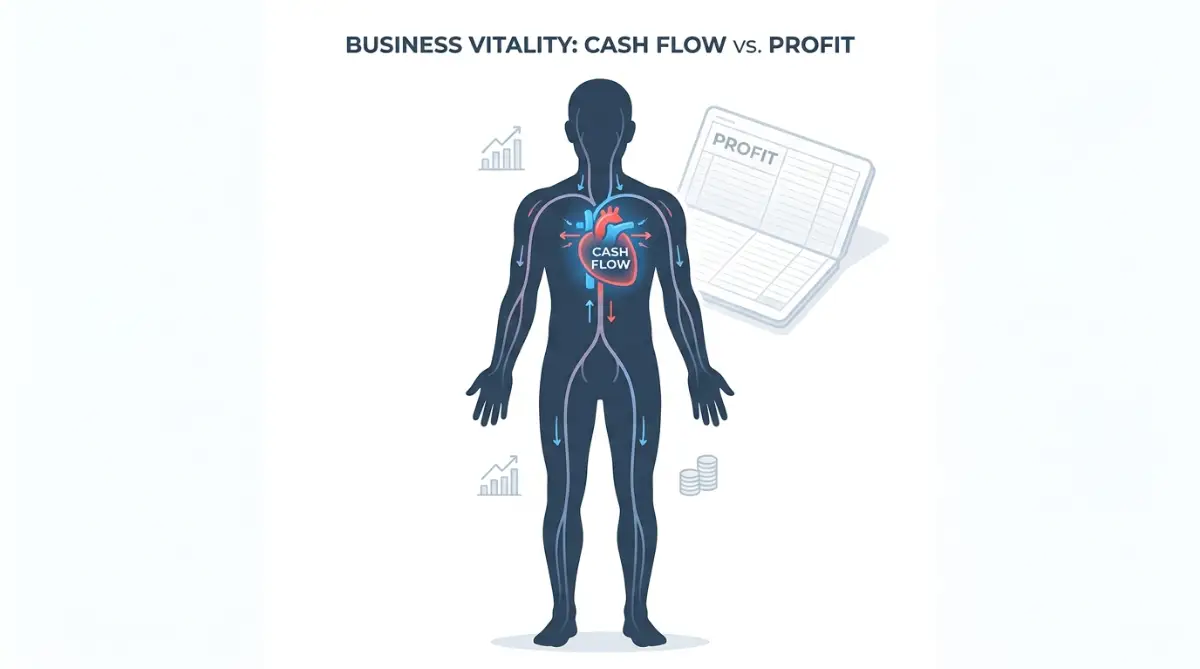
Think of your business like a human body. Cash is the oxygen. You can survive without eating (profit) for a while, but if you stop breathing (cash flow) for even a few minutes, you are in serious trouble. When you run out of cash, you cannot pivot, you cannot hire help, and you certainly cannot survive a bad month.
Why Your Business Bleeds Without You Noticing
Most businesses don't fail because they aren't good enough. They fail because they simply run out of air. There are several subtle ways your money disappears before it ever reaches your pocket.
The "Late Payment" Trap
You might have a great contract with big clients, but if they take three months to pay, you are stuck. You have already spent the money to deliver the service, but the return on that investment is trapped in an account payable department somewhere else.
Unseen Subscription Creep
It starts with one software tool for email. Then it’s a tool for design, another for analytics, and a third for project management. Suddenly, you have a "software tax" that drains your account every month, even when business is slow.
The Inventory Hoarding Habit
You might feel safer having a warehouse full of products "just in case." But that is just cash sitting on a shelf collecting dust. Inventory is expensive to store, insure, and manage, and it ties up the very cash you need to pay for marketing or payroll.
The Hidden Costs of Growth
Sometimes, growing too fast is actually the most dangerous move. If you sign five new big clients at once, you need to spend money on resources to support them long before they pay their first invoice. This is often called "overtrading," and it wipes out even the best business models.
Practical Steps to Master Your Money
You don't need a degree in finance to fix this. You need a system that gives you visibility and control. These steps are designed to turn your financial chaos into a predictable machine.
1. Build a Defensive Cash Buffer
Never operate on the edge. You should aim to have at least three to six months of basic operating expenses sitting in a separate account. This isn't "profit" that you spend; this is your safety net for when a client pays late or a market shift happens.
If you don't have this, start by saving a small percentage of every payment you receive immediately. Don't look at it as money to spend; look at it as insurance. When you have this buffer, you make smarter, more confident decisions because you aren't desperate.
2. Tighten Your Payment Terms
Why wait sixty days to get paid? You are not a bank. Move your standard payment terms to "Due on Receipt" or offer a small discount for early payment.
If a client insists on net-60 terms, make sure your pricing accounts for that delay. You can also implement a system where you require a deposit upfront. This covers your initial costs and confirms the client is serious about the project.
3. Conduct a Weekly Expense Audit
Most people look at their bank statements once a month, which is far too late to fix anything. Make it a ritual to review your cash outgoings every single week. Ask yourself: "Does this specific expense bring in more money, or is it just sitting there?"
If you haven't used a tool or service in the last thirty days, cancel it. You would be shocked at how many hundreds of dollars are wasted on forgotten subscriptions. Keep your spending lean until you have enough revenue to justify the "nice-to-have" expenses.
The "Weekly Audit" Checklist:
If you want to stop the "subscription tax," print this list and check it every Friday:
- Utility: Did I use this tool more than twice this week? (If no, cancel/pause).
- ROI: Does this tool save me money or make me money directly? (If no, delete).
- Redundancy: Do I have another tool that does this same job? (If yes, consolidate).
4. Forecast Your Cash, Not Just Your Sales
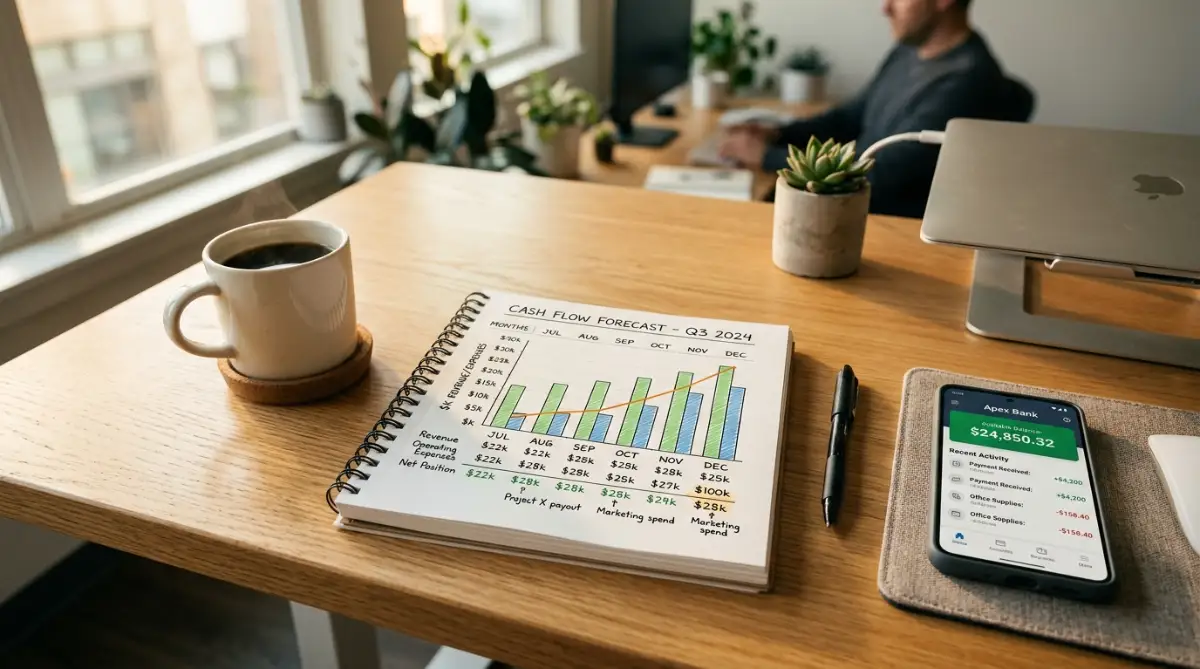
Most entrepreneurs are great at predicting sales. They think, "If I sell 100 units, I'll make X amount." But you need to forecast when that cash will hit your account.
Create a simple spreadsheet. List your expected income by the date you actually expect to receive the money. Then, list your bills by the date they are actually due. This will show you exactly which weeks you might face a shortfall.
[Pro Tip: The Power of My Own Realization]
I remember realizing I was paying for an expensive premium software plan because I was afraid of losing data, even though I only used 10% of its features. I switched to a cheaper version and saved enough to pay for my business internet for the whole year. My advice: audit your tools. If you don't use it, you don't need it. Don't let "what if" scenarios force you into paying for expensive features you aren't using.
You need to watch this video to understand how to structure your business expenses so you never run out of money again.
5. Separate Your Accounts Immediately
Never, under any circumstances, use your personal bank account for business transactions. It makes it impossible to see the real state of your business health. Open a dedicated business checking account and use it for everything business-related.
This creates a clear boundary. You can clearly see how much money the business has, independent of your personal life. When you keep them mixed, you are constantly guessing how much of your balance is actually "profit" versus "money you owe to taxes or vendors."
6. Focus on High-Margin, High-Speed Revenue
If your business has a mix of products or services, focus on the ones that bring cash back into your bank account the fastest. Some projects might look prestigious, but if they take six months to complete and payment comes at the end, they might be draining your resources.
Sometimes, you need to say no to big, slow-paying projects in favor of smaller, faster-paying ones. This is about survival. Once you have a mountain of cash in the bank, you can afford to take on the long-term, slow-burn projects.
7. Automate Your Invoicing
One of the biggest reasons for cash flow delays is that business owners forget to send the invoice. Or, they send it late, and the client takes their time processing it. Use an automated system that sends an invoice the moment a milestone is hit.
Many of these tools also send automated reminders if an invoice is overdue. This removes the awkwardness of you having to chase clients for money. The system acts as the "bad cop," and you stay the professional service provider.
Managing the Psychology of Finance
The biggest danger isn't just the math; it's the mental fatigue. When you don't have control over your cash, you spend all your time worrying instead of building. You stop being a CEO and start being a professional bill-payer.
By implementing these small, consistent systems, you reclaim your focus. You start to see the money as a tool that serves the business, not a master that controls your life. It allows you to breathe.
You will make mistakes. I have made plenty. But the goal is to make those mistakes small enough that they don't break you. Every dollar you track and every process you automate gives you more power over your future.
Stay disciplined with your spending, especially in the early stages. The temptation to spend on fancy office furniture or expensive branding is strong, but none of that matters if you can't cover your payroll next month. Stick to the basics, keep your cash liquid, and prioritize the survival of the business.
Your business is your marathon, not a sprint. If you manage your cash properly, you won't just survive the first year—you will be in a position of strength to thrive for years to come. Take it one week at a time, stay observant, and never let yourself fly blind when it comes to your financial health.
Beyond the Basics: Advanced Strategies to Secure Your Cash Flow
You have already learned the basics of keeping your money safe. Now, let’s look at the advanced tactics that keep the most successful business owners in the game for the long haul.
It is not enough to just track your money; you must learn how to manipulate the timing of your cash to your advantage. This is what we call the "Cash Conversion Cycle."
Think of your business like a fuel tank in a high-performance car. If you are burning fuel faster than you can refill the tank, you will eventually stall on the side of the road.
Mastering Your Cash Conversion Cycle
The goal is simple: collect money from your customers faster than you pay your vendors. If you pay your suppliers in thirty days, but your clients pay you in fifteen, you have a positive cycle.
You can learn more about how to manage these operational gaps by reading professional guides on how to bridge the professional skill gap by mastering basic automation tools. Using smart tools to track your invoices can save you hours of work.
If your cycle is reversed, you are essentially providing interest-free loans to your customers while you struggle to pay your own bills. To fix this, consider offering discounts for early payments. Even a two percent discount can entice clients to pay you weeks ahead of schedule.
The "What-If" Scenario Planning
I always tell new founders to build a "stress test" into their monthly routine. Ask yourself: "What happens if my biggest client stops paying for two months?"
You need to know your numbers well enough to have a Plan B ready. This is not about being a pessimist; it is about being a professional who respects the unpredictability of the market. You can look at specific business finance management resources to understand how government agencies suggest handling emergency funds.
When you have a plan for a bad month, you stop reacting with panic. You make calculated decisions based on data, not fear.
Why You Should Never Wait for Profit
Many new entrepreneurs wait until they see a profit on their statement before they start paying themselves. This is a trap that leads to burnout and resentment.
If you don't factor your own salary into your business expenses, you aren't actually running a business; you are running a hobby that costs you money. Even if you start with a small amount, paying yourself creates a professional boundary.
If your revenue is truly stalled, you might want to understand the passive income fallacy and why your online revenue is stalled. It helps to separate "busy work" from work that actually brings money into the bank.
Managing Seasonal Dips Like a Pro
If your business has a slow season, do not wait until the slow season starts to prepare. You should be saving a portion of your revenue during the "fat" months specifically for the "lean" months.
Treat your business account like a reservoir. In the rainy season, you fill it up so that you have water during the dry season. This simple act removes the stress of wondering how you will pay your rent when business inevitably slows down.
For more insights on maintaining stability, you can check out three rules for better cash flow which highlights how top-performing companies handle their liquid assets. It is a great way to see how experts structure their finances.
The Dangerous Pitfalls That Keep Founders Awake
There is a specific kind of pain that comes with watching your business balance hit zero. I have felt it, and I know many others who have too.
It often starts with small, seemingly harmless choices that snowball into a mountain of debt. Let’s talk about the traps that catch most people by surprise.
The Myth of "The Next Big Sale"
One of the biggest mistakes is betting the entire future of your business on a single, massive client or project. You spend all your cash reserves to land this "big fish," assuming the payoff will solve everything.
But what happens if the payment is delayed? Or what if the client asks for endless revisions, tying up your resources for months?
Suddenly, you are broke, you are overworked, and your other, smaller clients have been ignored. You lose the foundation of your business while chasing a dream that hasn't arrived yet.
Mixing Personal and Business Funds
I see this far too often. It feels easier to just use your personal debit card for a business expense or your business credit card to grab lunch with a friend.
This "commingling" of funds is a recipe for disaster. It hides your true financial performance, making it impossible to see where your money is actually going.
You lose the ability to track your real profit margins because your personal and business expenses are blurred. You will eventually face a tax nightmare because you cannot prove which transactions were for the business and which were for your personal life.
The "Shiny Object" Spending Syndrome
It is so tempting to spend money on things that make you "look" successful. You want the expensive logo, the fancy website, or the premium office software because you think it will help you land more clients.
But your clients do not care about your fancy letterhead. They care about the value you provide and the results you deliver.
Spending money on "nice-to-haves" before you have "must-have" revenue is a fast track to insolvency. Keep your overhead as low as possible until you have consistent cash coming in.
Ignoring Your Mental Health in the Process
The financial stress of a struggling business takes a real toll on your health. You might find yourself losing sleep, skipping meals, and snapping at your loved ones.
It is easy to push this aside, but why mental health check-ups are just as essential as physical screenings is a topic you cannot ignore. If you burn out, your business burns out with you.
You are the engine of your company. If you are not functioning, nothing else matters. Take breaks, talk to someone, and remember that no amount of money is worth your sanity.
Failing to Invoice Immediately
I have known business owners who deliver a perfect project but wait two weeks to send the invoice. They feel "awkward" asking for money.
This is a professional relationship, not a social one. When you delay your invoicing, you are telling the client that the money is not a priority.
Send your invoice the moment the work is complete. You can read a breakdown of how to understand the gap between billing and getting paid to see why timing matters so much.
Your Roadmap to Financial Freedom
Mastering your cash flow is not just about math; it is about freedom. When you have control over your finances, you have the freedom to make choices.
You choose which clients to work with. You choose when to grow. You choose when to take a vacation.
If you don't control your money, your money controls you. It dictates your mood, your sleep, and your future.
Start Your Action Plan Today
Do not try to fix everything at once. Start by opening a dedicated bank account if you haven't already.
Then, commit to one hour every week to review your numbers. Look at what came in, what went out, and what is due next week.
Consistency is your best friend here. You don't need to be a financial genius to win this game; you just need to be present and aware of your situation.
My Personal Promise to You
I know how heavy the weight of financial uncertainty can feel. I have been in the exact same spot, questioning every decision I made.
But I also know that you have the power to turn this around. Take these steps, be honest with your data, and keep pushing forward.
You are building something valuable, and you deserve to see it thrive. Take a deep breath, look at your numbers, and start making the moves that will secure your business for the long term.
Common Questions About Managing Your Cash
Why does my bank balance never match my profit reports?
Profit and cash are two different things. Profit includes money you have earned but haven't collected yet, while your bank balance only shows the cash you actually have in hand right now.
How much cash buffer is safe to keep?
Most experts recommend keeping three to six months of your operating expenses in a separate, liquid account. This ensures you can cover your costs even if you don't make a single sale for a few months.
Should I pay off debt or save cash first?
It is usually better to maintain a small cash buffer first so you don't have to borrow more money if an emergency happens. Once you have a safety net, you can use your excess cash to pay down high-interest debt aggressively.
What is the biggest sign that I have a cash flow problem?
If you are constantly scrambling to pay bills that are due this week even though you have work lined up for next month, you have a timing gap. You need to focus on collecting payments faster or renegotiating your vendor terms.
Disclaimer: The information provided in this article is for educational purposes only and does not constitute professional financial or legal advice. Every business situation is unique, and you should consult with a qualified accountant or financial advisor to discuss your specific needs before making major financial decisions.