The Frustrating Mystery of the Renewal Notice
You open an envelope from your insurance company, expecting a standard statement, but the number staring back at you makes your coffee go cold. It’s higher than last year, and there is absolutely no explanation for why. If you’re tired of feeling like a random number on a corporate spreadsheet, it’s time to stop paying blindly and start understanding how your risk profile is actually calculated.
I spent that entire afternoon scouring the internet, trying to find out why. I wanted to know who decided that I was suddenly more expensive to insure. It felt like a game where the rules were hidden from me, and every time I tried to ask for a clear answer, I got brushed off with jargon and "company policy." My stress levels were through the roof, and I honestly felt trapped. I realized then that most of us are just blindly paying these bills without having the slightest clue about how the system actually decides our value.
The Math Behind the Curtain
It all starts with something called "Risk Pooling." Insurance companies take thousands of people and put them into a group. If you share similar characteristics with others in that group—like living in the same area or driving the same type of car—you get lumped together. The underwriter looks at the past data of that entire group to predict the future cost of the entire group.
This is why your rate can change even if you haven't done anything wrong. If everyone in your neighborhood suddenly starts filing more claims for storm damage, the risk for your entire "pool" goes up. The underwriter sees that trend, realizes the risk is higher, and adjusts the premiums for everyone in your zip code.
It feels unfair, but from their perspective, it is just balancing the books.
Data Points You Didn't Know Were Being Tracked
We often think the only thing that matters is our claims history. But modern underwriting is a massive engine of Big Data.
Quick Insurance Audit Checklist:
- Update your coverage: Have you added security features to your home? Tell your insurer!
- Check your credit report: Is there an error dragging your score down? Fix it.
- Ask for discounts: Did you complete a defensive driving course? Ask about lower rates.
- Review usage: Does your policy list the correct annual mileage for your car?
They are looking at your credit score, your occupation, the age of your roof, the distance between your home and the nearest fire station, and even how often you let your insurance lapse.
Some companies now use telematics, which are those little devices or apps that track your driving behavior. They aren't just checking if you speed. They are checking how hard you brake, how quickly you accelerate, and what time of day you are on the road. All of this information feeds back into their underwriting models to refine your specific risk score.
Why Your "Safe" Behavior Might Not Lower Costs
This is where the struggle gets real. You might think, "I haven't had an accident in five years, so my rates should be dropping." But the underwriter is looking at the cost of accidents, not just the frequency. If the cost of parts to fix your car has skyrocketed due to inflation, the underwriter has to account for that.
Even if you are the perfect driver, the rising cost of medical care and legal services means that when an accident does happen, the payout is much higher. The underwriter builds this into the premium structure. You are paying for the statistical probability of a high-cost event, not just the probability of an accident occurring.
The Insurance Insider’s Guide
- Risk Pooling: Your rates depend on the group, but your individual habits can earn you discounts.
- Big Data: Insurers look at everything from credit scores to how you brake your car.
- Active Partner: Being proactive with your agent can lead to lower rates.
- Deductible Swap: A higher deductible can significantly lower your monthly premium if you have a solid emergency fund.
Getting Smart About Your Underwriting Profile
You cannot change the past, but you can definitely manage how you are perceived by these underwriting systems. The goal is to make yourself look like a "low-risk" asset. Here is how you can effectively influence the variables that are within your control.
Tidy Up Your Financial Reputation
Your credit history can play a role in insurance pricing, particularly for auto and home insurance in places where insurers are allowed to use credit-based insurance information. A lower credit profile may be associated with higher premiums, although the rules and impact vary depending on where you live and which insurer you use.
If your credit has taken a hit, it is worth taking steps to improve it rather than simply ignoring the problem. Check your credit reports for errors, pay bills on time, reduce outstanding balances when possible, and contact creditors if you're having trouble keeping up with payments.
Improving your credit usually takes time, but consistent progress can strengthen your overall financial position. In some insurance markets, it may also help improve the credit-related factors used when your premium is calculated.
The Importance of Home Maintenance
When it comes to home insurance, the underwriter looks at the physical condition of your asset. They are terrified of small problems turning into catastrophic claims. A small leak in your roof today is a massive water damage claim tomorrow. They see that as a liability.
By documenting your home improvements—like replacing an old roof, upgrading your plumbing, or installing a security system—you give the underwriter something concrete to work with. Don't just do the work; tell your insurer about it. Send them the receipts and the certificates. It provides a narrative of a responsible homeowner who takes care of their property, which is exactly what they want to see.
Reviewing Your Coverage Limits
Sometimes, we are paying for coverage we don't actually need. If your car is ten years old, do you really need the highest level of collision coverage? The underwriter sets your rate based on the maximum payout they might have to make. If you lower that maximum payout by adjusting your limits, your premium will naturally drop.
This is a balancing act. You don't want to be under-insured, but you also don't want to pay for a "Cadillac" policy on a "bicycle" asset. Sit down with your policy documents and look at the declarations page. Ask yourself if those numbers still make sense for your current reality.
[Pro Tip: My Realization]
I once realized I was paying extra for a policy rider that covered equipment I had sold years ago. My biggest mistake was being lazy with my paperwork; I assumed the system would "just know" things had changed. I learned that I have to be the one to update the insurer, because the underwriting system only knows what you tell it.
The Value of Being an Active Partner
Don't wait for your renewal to talk to your insurance company. If you have done something to improve your risk profile, make sure they know. Whether it is installing a smart home device that monitors for leaks or completing a defensive driving course, these are tangible updates to your file.
When you act as an active partner, you stop being just another file number and start being a client with a history. While the underwriting process is largely automated, having a good relationship with an agent who can advocate for you and update your details manually is a secret weapon that many people ignore.
This video breaks down how risk assessment works in the insurance industry, helping you understand the factors that drive your premiums.
Navigating the "Loss Ratio" Reality
There is a concept in insurance called the "Loss Ratio." It is the amount of money an insurer pays out in claims divided by the money they take in from premiums. If your specific policy or your specific region has a high loss ratio, the underwriter must raise rates to keep the company solvent.
This is why you can be a perfect policyholder and still see your rates jump if you live in a disaster-prone area. If there have been hurricanes, floods, or wildfires in your region, the entire pool is affected. You can't change the weather, but you can change your readiness.
The Importance of Deductibles
Your deductible is your personal "stake" in the risk. If you choose a higher deductible, you are telling the underwriter that you are willing to take on more of the small financial burden. In exchange, the insurance company reduces your premium. It is a direct trade-off of risk.
If you have an emergency fund, raising your deductible is often one of the fastest ways to lower your monthly premium. It discourages you from filing small, petty claims, which keeps your personal risk profile "cleaner" in the eyes of the underwriter. A cleaner profile means lower rates in the long run.
Challenging the Underwriter's Assumptions
Did you know you can sometimes challenge a premium increase? If you see a surcharge on your policy for something that doesn't exist—like a discount you should be getting but aren't, or a claim on your report that isn't yours—you have the right to ask for a correction.
Mistakes in the underwriting data pool happen more often than you think. Humans make data entry errors, and algorithms can sometimes misinterpret addresses or histories. If you see a charge that doesn't make sense, call and ask for a line-by-line explanation. It is your money, and you have every right to understand exactly what you are paying for.
The Role of Independent Agents
If you are dealing directly with a massive insurance carrier via a website, you are often dealing with pure, unadulterated algorithms. There is no nuance, and there is no flexibility. This is where independent insurance agents become an asset.
An independent agent works with multiple insurance companies. They can shop your profile around to different underwriters, each of whom uses a different proprietary model to set rates. What one underwriter considers a "high risk," another might consider "standard." Finding an underwriter whose model favors your specific lifestyle is often the key to getting a better rate.
Staying Consistent Over Time
Consistency is the name of the game. Underwriters love a long history with one company. It provides them with a clear, reliable picture of your behavior. Jumping from one insurance carrier to another every six months makes you look like a "hopper," which can actually hurt your risk score.
If you find a good company, try to stick with them. They will accumulate data on you, and if you are a low-risk client, they will be motivated to keep you. Loyalty isn't just a virtue; in the world of insurance, it is a data point that can translate into discounts and better underwriting terms.
Preparing for the Long Term
Managing your insurance costs is not a one-time project. It is a maintenance habit. Just like you check your bank account or monitor your health, you need to check your insurance status annually. Review your coverage, update your personal data, and keep an eye on your credit score.
Think of it as tending to a garden. If you let the weeds grow (missed updates, bad credit, high-risk lifestyle choices), the "cost of the garden" goes up. If you prune the weeds and care for the soil, the long-term cost remains manageable. You are in control of more than you think.
Final Thoughts on Insurance Clarity
Understanding the underwriting process is empowering. It moves you from a place of fear and confusion to a place of knowledge and action. You are not just a victim of rising rates; you are a participant in a financial system that rewards predictability and low risk.
Every step you take to lower your risk—from driving safely to keeping your home well-maintained—is a signal to the insurance carrier that you are a partner in loss prevention. Keep your documents in order, stay vigilant with your financial health, and don't be afraid to ask questions. Your future premiums depend on the actions you take today.
You have all the information you need to start navigating this space with confidence. Treat your insurance policy as a living document, keep your habits clean, and you will see the results reflected in your statement over time. It is a process that requires patience, but the long-term savings are worth every bit of the effort.
Mastering the Game of Risk and Predictability
You might assume that insurance companies are just guessing your rates, but the process is actually a very refined science. Underwriters are essentially betting on the likelihood that you will have a stable, low-risk future. If you want to keep your costs down, you need to make it as easy as possible for them to see you as a safe bet.
One of the most effective secrets is maintaining a clean "risk history." This means avoiding small, frequent claims. If you have a leaky pipe, fix it yourself rather than filing a claim for every minor issue. A history of small claims can sometimes make an underwriter worry that you are a high-maintenance client who will be expensive to support long-term.
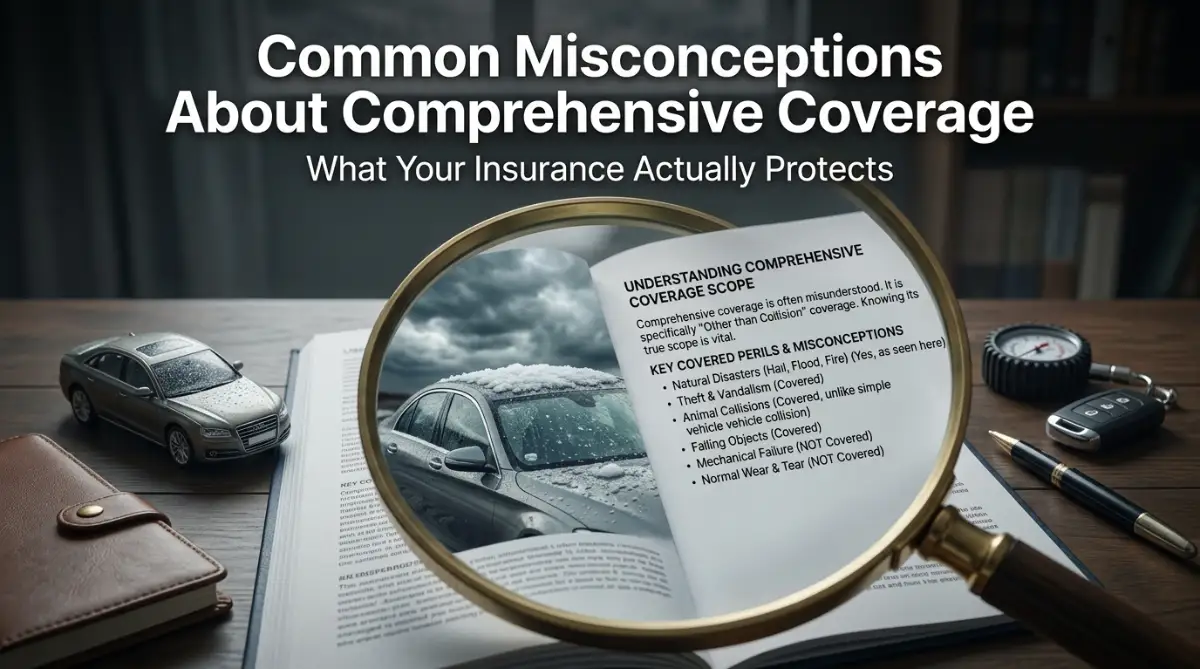
It is also helpful to understand how insurance works on a broader scale, which gives you a better perspective on why these systems prioritize stability. When you view your policy as a long-term asset rather than a "get out of jail free" card, your behavior changes. You become more careful, and your risk profile naturally improves.
Another expert secret involves your deductible. If you have a healthy emergency fund, you should consider increasing your deductible to the highest amount you can comfortably afford. This simple move often signals to the insurer that you are financially stable and responsible. It can drastically lower your monthly premium, as shown in guides about understanding the gap between out-of-pocket limits and your overall coverage.
Finally, communicate with your agent regularly. They are your translator in this complicated process. If you have upgraded your home security or improved your driving safety record, make sure they put that in your file. These small details often get missed by automated systems, and a personal touch can sometimes be the difference between a rate hike and a steady premium.
The Invisible Traps That Drive Your Premiums Up
Many people believe they are playing by the rules, but they unknowingly sabotage their own rates with simple, avoidable errors. The biggest pitfall is the "Omission Trap." This happens when you fail to disclose a past event or a change in your living situation because you think it is irrelevant.
Underwriters thrive on accuracy. If they discover something later that you failed to mention, they view it as a red flag regarding your honesty. Once you are flagged as "high risk" due to a lack of transparency, your premiums will almost always skyrocket. Honesty really is the best policy here, even if it feels like you are hurting your chances.
Another massive mistake is ignoring the fine print of your policy until a problem occurs. I see so many people shocked when they find out their specific type of water damage or theft is excluded. They then end up dealing with denied insurance claims, which leaves them with a huge out-of-pocket loss. Always know what you are buying before you commit.
Don't let the stress of insurance costs distract you from your broader financial goals, either. People often panic and start making bad moves, like handling market volatility by selling off assets to pay for a premium spike. Stay calm, look at your numbers, and make decisions that protect your long-term wealth, not just your short-term cash flow.
Finally, watch out for the "Set it and Forget it" mentality. If you haven't shopped your insurance in years, you are likely paying a loyalty penalty. Underwriters often raise rates on older policies because they know the customer is too busy or too comfortable to switch. Be the customer who audits their own expenses at least once a year.
Your Path to a Smoother Insurance Journey
You have the power to change how the system perceives you. Start by taking control of your data and being more proactive about your own risk management. If you feel confused, take a moment to educate yourself on the basics, like decoding medical bills or understanding your policy declarations.
Remember that insurance is a tool for peace of mind, not a source of constant anxiety. By keeping your claims history clean, your credit score healthy, and your documentation up to date, you become the ideal client. You are essentially teaching the underwriting algorithm to like you.
I have spent years managing my own policies, and I used to feel just as frustrated as you might feel today. But I learned that once I stopped seeing the insurance company as an enemy and started seeing them as a partner, everything changed. I started paying attention to the details, and my premiums finally leveled out. You have the ability to do the exact same thing, and I know you can take charge of your financial safety starting today.
Common Questions About Insurance Underwriting
Can I actually talk to an underwriter to lower my rate?
In most cases, you cannot talk to the underwriter directly because they work behind the scenes. However, you can talk to your insurance agent, who acts as your advocate. They can provide the necessary context to the underwriter to help reconsider your risk profile.
Why does my rate go up if I haven't filed a claim?
Insurance premiums are based on group risk, not just your individual behavior. If your neighbors file many claims or if the cost of repair materials rises in your area, your premium may increase to cover the collective risk of the group.
Does my credit score really affect my home insurance?
Yes, in many regions, insurers use credit-based insurance scores. They have found that people who manage their finances responsibly are statistically less likely to file claims, so they offer lower rates to those with higher scores.
How often should I check my insurance policy?
You should review your insurance coverage at least once every twelve months. This allows you to update your information, look for new discounts, and adjust your coverage based on your current lifestyle and asset value.
What should I do if I think my premium increase is a mistake?
Call your insurance company immediately and ask for a detailed explanation of the rate change. If you suspect an error in their data, request a formal review of your policy information to ensure all your details are accurate.
Disclaimer: This article is for informational purposes only and does not constitute professional legal, financial, or insurance advice. Every policy and underwriting model is unique, and individual circumstances can vary greatly. Always consult with a licensed insurance professional or a qualified financial advisor in your specific region before making changes to your coverage or financial plans.