
When Healthcare Feels Like a Maze
Most people treat health insurance like a tax return—they put it off until the last minute because it feels like a headache. You aren’t looking for a lecture on medical terms; you just want to know that when you get sick, your bills won't wipe out your savings. I have spent years untangling these complex plans, and today, I am going to show you how to cut through the confusion so you can pick a plan that actually works for your life.
That feeling of helplessness is something I know many of you have faced. You want to protect your health and your savings, but the system often feels like it is built to keep you guessing. It is not just about the paperwork; it is about the constant worry that you might miss a detail that could cost you later. Many people tell me that they end up picking a plan just to stop the stress, rather than picking the one that truly fits their life. This leads to sleepless nights and a nagging sense of doubt every time a medical bill arrives in the mail.
It is heartbreaking to see so many good people struggle with these choices. You deserve to feel confident and secure in your healthcare decisions. When you do not understand your options, your peace of mind disappears, and your daily life becomes clouded by "what-ifs." I am here to help you clear that fog and make this process much simpler. Let us break this down together so you can stop worrying and start choosing with clarity.
 Breaking Down the Medicare Puzzle
Choosing the right plan does not have to be a nightmare if we tackle it one step at a time. The first thing you need to do is look at your own health history and your typical medical needs. Write down the names of your current medications and how often you visit a doctor. Knowing your own "usage pattern" is the best way to cut through the marketing noise of different plans. When you have this list, you can compare plans based on what you actually need, not just what a brochure suggests.
Mapping Your Personal Health Needs
Medicare: Myth vs. Reality
Start by creating a simple chart. List your regular doctors on one side and your medications on the other. Now, check if those doctors are in the network for the plans you are considering. Network compatibility is one of the most common spots where people get stuck. If your favorite doctor is not covered, a plan that looks cheap on paper might end up being very expensive for you.
Pro Tip: My Personal Lesson Learned
I once made the mistake of picking a plan based solely on the monthly premium, thinking I would save money. I realized too late that my regular specialist was out-of-network, which ended up costing me hundreds more in out-of-pocket fees. My advice to you is to always prioritize your doctor's list over the monthly price tag, because consistent care is worth more than a few dollars saved.
The "Annual Coverage" Checklist (Before You Sign)
Doctor Check: Have I verified that my main specialists are currently in-network for the coming year?
Medication Audit: Are all my current prescriptions on the plan’s formulary list?
Emergency Fund: Do I have enough saved to cover the out-of-pocket maximum if something goes wrong?
Benefit Match: Does this plan offer the specific wellness perks I will actually use?
The Power of Comparing Costs vs. Benefits
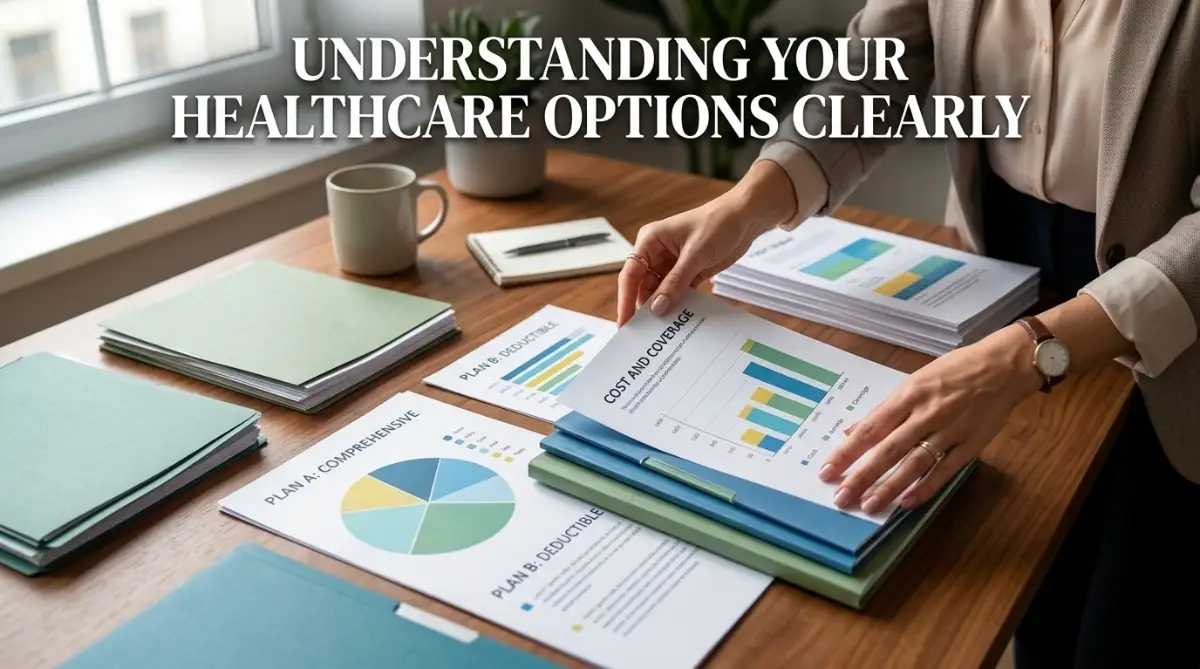
You need to look beyond the premium. Focus on the out-of-pocket maximum and co-payments. Think of it as a balance; a low monthly premium often means higher costs when you actually go to the doctor. A higher premium might be a better deal if you have frequent medical needs. Use a simple calculator or even a notepad to do the math for your specific situation. This small effort gives you the power to see the real cost of each plan.
Understanding Plan Tiers and Coverage
Every plan has different "tiers" for medications. You need to verify if your specific drugs are on the formulary—the list of covered drugs—for the plan you like. Sometimes, a drug that is covered on one plan might have a very high co-pay on another. Check this carefully before signing up, as it changes how you budget for your health.
Why Checking the Fine Print Matters
Never rely solely on what a friend or a TV commercial tells you. Each person's situation is unique, and what works for your neighbor might be a disaster for you. Always spend thirty minutes reading the "Summary of Benefits" for any plan you are seriously considering. This document is written for you to understand, and it holds the truth about what is really covered.
How to Get Expert Support Without the Sales Pitch
If you feel stuck, seek out local advisors who are not there to sell you a specific product. Many community centers or public agencies offer free, unbiased guidance. Ask them questions about the plans you have narrowed down. Having a second pair of eyes on your choices can prevent simple, costly errors.
If you want a visual breakdown of how these choices affect your monthly budget, check out this video below.
This video walks you through the exact steps of comparing plan costs, helping you make a decision that fits your specific needs perfectly.
Tracking Your Coverage Over Time
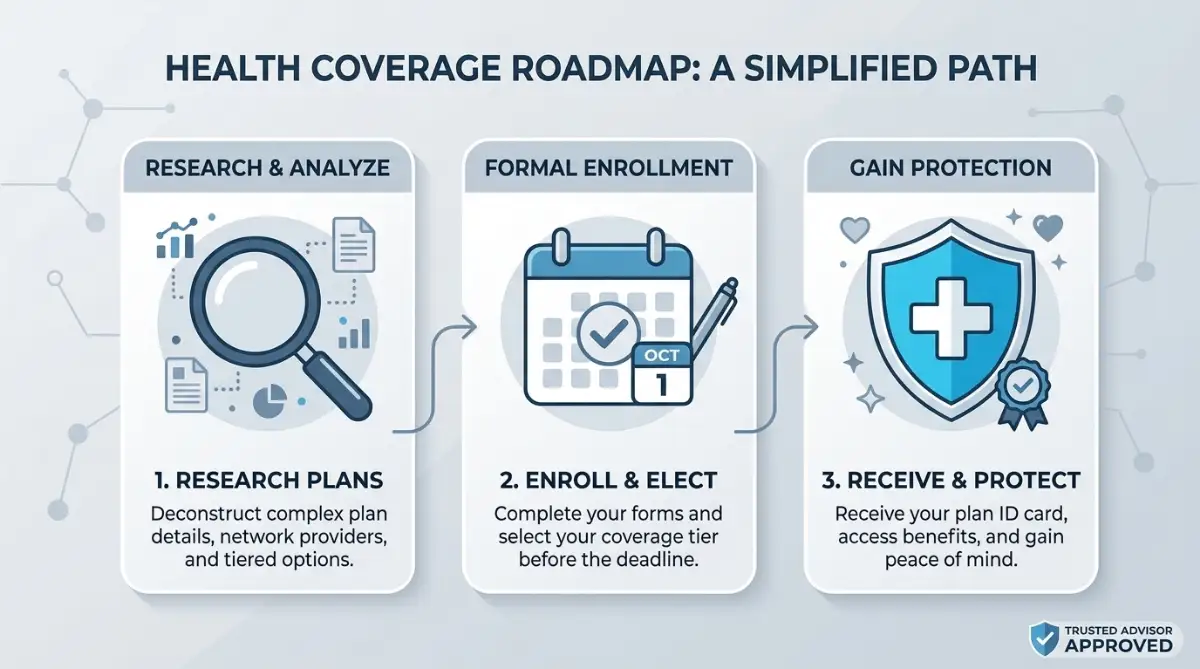 Your health needs might change next year, and that is okay. You are not locked into a bad choice forever. Set a reminder to review your coverage once a year during the open enrollment period. Staying proactive ensures that your plan still works for your current health reality, keeping your finances stable and your mind at ease.
Building Your Confidence in Healthcare Decisions
You have an important role in your own healthcare decisions. You don't have to understand everything at once or make every decision on your own. Asking questions, reviewing your options, and discussing concerns with a qualified healthcare professional can help you make choices that fit your needs and circumstances.
Small, practical steps—such as understanding your treatment options, checking costs, keeping track of medications, and speaking up when something is unclear—can make healthcare feel more manageable. Take your time when you can, use reliable information, and don't hesitate to ask for clarification when you need it.
The goal isn't to make every decision perfectly. It's to become more informed and comfortable participating in decisions that affect your health, both now and in the future.
Mastering Your Coverage for Long-Term Peace of Mind
Navigating health insurance requires more than just picking a plan; it requires a strategy for the road ahead. One of the best secrets I have discovered is the habit of keeping a personal medical log. Whenever you visit a clinic or buy a prescription, jot down the date, the service received, and any out-of-pocket costs you paid. Over a few months, this simple notebook becomes a goldmine of data that helps you predict your actual needs for the next year.
Another advanced tip is to look at the "Summary of Benefits and Coverage" (SBC) document provided by every insurer. You can find these documents often hosted on official government portals like Medicare.gov to get a standardized view of what a plan offers. Do not just look at the shiny brochures. The SBC is a legal requirement that forces companies to show you exactly what they pay and what you pay in a clear, side-by-side format.
If you find yourself struggling with complex financial choices, it is often helpful to start by managing your personal budget more effectively. When your finances are organized, you can clearly see how much you can afford to spend on premiums versus potential medical bills. Sometimes, spending a little more on a monthly premium is the smartest way to stay protected from surprise expenses later.
You should also check if your plan offers "extra perks" like wellness programs or gym discounts. Many people ignore these, but they can significantly improve your quality of life without costing you an extra dime. Always double-check your account settings, just as you would when keeping your online bank accounts safe. Security and clarity are the two pillars of a stress-free experience.
Finally, do not be afraid to switch plans if your situation changes. You are not stuck. If you feel like your current choice is no longer serving you, it might be time to look for a better fit. You can find helpful resources on understanding your rights as a patient through official health department guides. By staying active and informed, you make sure your healthcare plan actually works for you.
Pitfalls That Trip Up Even the Best Planners
The most common mistake people make is falling in love with the "lowest monthly price." I have seen so many individuals pick a plan because the monthly bill looked small, only to find out their deductible was massive. When a health issue actually pops up, they are left with a bill they cannot pay. It is a trap that feels like a bargain until the moment you need care.
Another major error is ignoring the network changes. You might have a plan that covers your favorite doctor this year, but networks shift and change. If you do not check the provider list during the renewal period, you might walk into an appointment only to find out you are suddenly "out-of-network." Always verify your doctor’s status every single year, as if you were managing hidden background processes to keep things running smoothly.
Many also fail to understand the difference between a co-pay and coinsurance. A co-pay is a set dollar amount, while coinsurance is a percentage of the total cost. If you are not careful, you might be shocked by a high bill for a simple test because you didn't realize you were paying a percentage. This kind of confusion often leads to syncing problems in your financial planning, making it hard to predict your monthly expenses.
Finally, some people just sign up without reading the "evidence of coverage" document. It feels boring, but it is the only place where the fine print is truly explained. If you skip this, you might end up in a situation where you are surprised by what isn't covered. Avoiding these traps is like fixing critical mistakes in your privacy settings—it takes a moment to check, but it saves you a world of trouble later.
Your Path to Healthcare Confidence
Choosing the right path for your health is a journey toward peace of mind. By focusing on your specific needs and staying updated with your plan details, you take full control of your future. You are now equipped with the knowledge to look past the marketing and see the real value of your options. Keep your documents organized, stay curious about your benefits, and never hesitate to ask for professional help if you feel unsure.
I have walked this path myself, and I know that the hardest part is just taking that first step toward understanding. Once you start looking at the details, the fear disappears and is replaced by a sense of calm strength. You have everything you need to make the right choice today, so trust your research and move forward with confidence.
Questions You Might Have
Can I change my plan if I find a better one later?
Yes, you generally have a set time each year to switch plans, known as the open enrollment period. It is always wise to review your needs when this time comes to see if a better option exists for your health and budget.
Does a plan with a higher premium always mean better coverage?
Not always, but it often means you pay less when you receive medical services. You have to weigh your monthly budget against how often you expect to visit doctors or need medications.
Where can I find unbiased information about my options?
You can look at government websites or reach out to local community resources that specialize in non-profit health counseling. These sources provide clear, facts-only data to help you decide.
What should I do if my doctor stops taking my insurance?
You should contact your plan provider to see if there is an issue with the network agreement. If the doctor truly leaves the network, you may need to look for a new provider or consider a plan change during the next enrollment window.
Disclaimer: This content is for informational purposes only and does not constitute professional medical, legal, or financial advice. Always consult with a licensed professional or official government agency before making decisions regarding your healthcare coverage.
Thank you for reading. At Finliora, our mission is to provide accurate, practical, and trustworthy information to help you make informed decisions with confidence.