The Tug-of-War Inside My Bank Account
I still remember the night I sat down with a calculator and my two most pressing financial concerns: a persistent credit card balance and an empty retirement account. It felt like I was trying to fill a bucket with a hole in the bottom. Every dollar I put toward the debt felt like a dollar that wasn't growing for my future. And every dollar I put into my savings felt like I was ignoring the interest fire burning through my debt.
It was an exhausting mental battle. I wanted to be "the responsible adult," but I had no idea which path was the right one. I spent weeks reading conflicting advice. Some people told me to ignore everything else and kill the debt with fire. Others said that if I didn't start my retirement fund right away, I would lose the magic of time.
I felt like I was failing at both tasks. My debt wasn't disappearing fast enough, and my retirement balance looked like a joke. That feeling of being stretched too thin is something I hear from so many of my peers. It creates a quiet panic. You start to doubt your ability to ever reach that finish line of freedom.
The reality is that money management isn't a single switch you flip. It is a balancing act. The stress comes from thinking there is only one "right" way to do things. I realized that my anxiety was actually hurting my finances more than the debt itself. Once I stopped looking for a perfect answer and started looking for a balanced strategy, the weight on my chest finally began to lift.
The Math Behind the Balancing Act
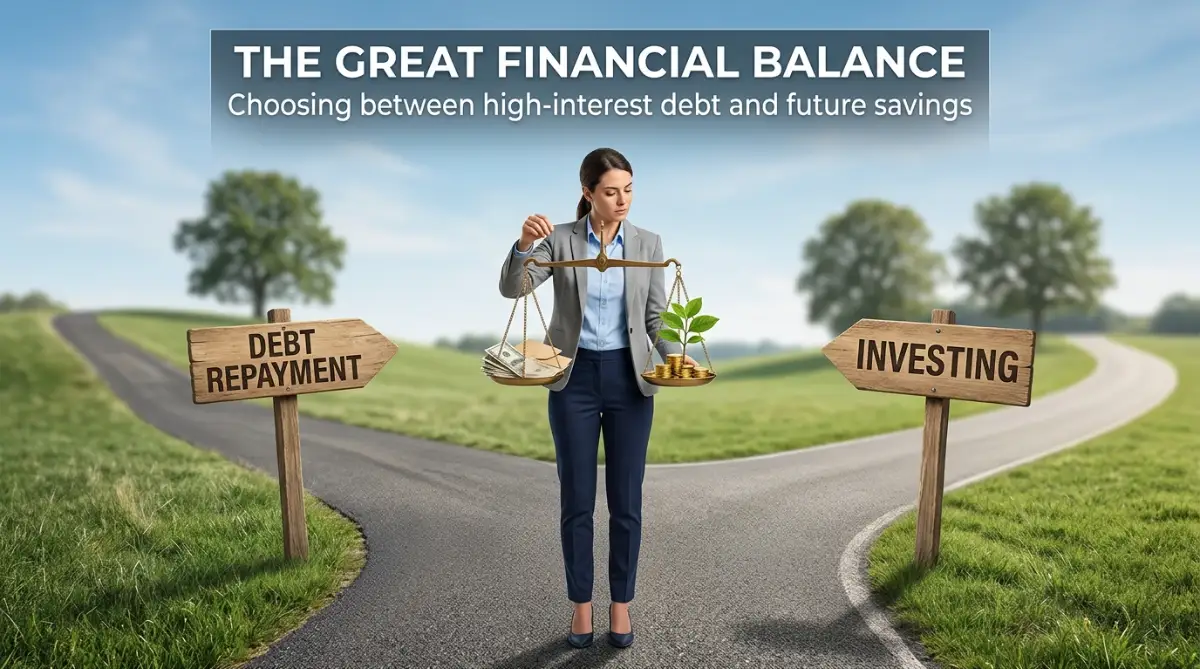
We often get stuck in the "all or nothing" trap. We think we have to choose between paying off debt and saving for retirement. But in the real world, you can—and often should—do both. The secret lies in understanding the numbers behind your interest rates.
Understanding the 5% Threshold
If your debt has an interest rate above a certain level—let's say 5% or 6%—it is an emergency. Why? Because it is very hard to earn a guaranteed 6% return in the stock market consistently. If you pay off that debt, you are effectively "earning" 6% because you aren't losing it to interest anymore. This is a guaranteed win.
On the other hand, if you have low-interest debt, like a student loan at 3%, you might be better off investing. Why? Because long-term stock market returns often average higher than 3%. In this case, your money might actually grow more if you invest it rather than paying off the low-interest loan. It is about where your dollar works hardest.
The Employer Match: Free Money
There is one massive exception to the "pay off debt first" rule. If your employer offers a retirement match, take it. This is free money. If you put in 3% and they put in 3%, that is an immediate 100% return on your investment. No debt interest rate—short of a predatory payday loan—can beat a 100% return.
Always prioritize the employer match before you make any extra payments on your debt. It is the only time where you should definitely invest while carrying debt. Missing out on a match is literally throwing money away. It is one of the most basic moves, yet so many people miss it because they are too focused on the debt number.
The Psychology of Momentum
Math matters, but feelings matter too. If you carry debt, you feel a sense of failure. If you don't have a retirement account, you feel a sense of dread about the future. You need to find a balance that lets you sleep at night. If paying off a small debt makes you feel like a champion, do it. That feeling of victory is worth more than the few dollars you might gain in interest by investing instead.
Step 1: Secure the Employer Match
Before you add an extra cent to your credit card or loan, ensure you are getting the full match from your employer. This is non-negotiable. Set your contribution to the minimum percentage required to get the maximum match. This secures your growth without needing a massive monthly commitment.
Step 2: Tackle the High-Interest Debt
Now, look at your debts. Any debt with an interest rate above 7% or 8% needs to be attacked. Use the extra money you have each month to pay these down. Do not worry about "saving" at this point. You are stopping a financial leak. This is the most efficient way to clean up your balance sheet.
Step 3: Build a Small Buffer
You don't need a massive emergency fund while you are in debt, but you do need a small one. Save one thousand dollars in a separate account. This prevents you from running back to the credit card when a flat tire happens. It keeps your debt repayment plan on track. It is your shield against the unexpected.
Step 4: The Balanced Growth Phase
Once the high-interest debt is gone and your buffer is in place, you can shift gears. Now, you can increase your retirement contributions to 10% or 15%. At the same time, you can slowly chip away at any low-interest debt you might have left. You are now doing both: building your future and clearing your past.
Pro Tip: What I Learned About Debt and My Future
I used to believe that paying off debt as quickly as possible was always the right thing to do. I was actually proud of how quickly I was getting rid of my loans.
Then I checked my retirement account and realized something that changed the way I looked at money. By waiting two years to start investing, I had also missed out on potential long-term growth.
That made me rethink my approach. I didn't need to put every extra dollar toward my debt just to feel like I was making progress. I could have paid a little less toward the loans while still putting some money into my retirement account.
The biggest lesson for me was that debt repayment and investing don't always have to be an either-or choice. Depending on your interest rates and financial situation, you may be able to make progress on your debt while also giving your future savings a chance to grow.
The Power of Automated Habits
The key to all of this is automation. If you have to make a choice every month, you will choose the easiest path, which is usually spending. Set up your bank to move the money for you. Let the system do the heavy lifting. You want to make it so that your savings and debt payments happen whether you are awake or asleep. That is how you win.
"Your 5-Minute Monthly Debt Check-up:
- Update your balances in your spreadsheet.
- Calculate how much interest you saved this month.
- Check your calendar: Are there any big expenses coming up?
- If you have extra cash, make the payment today—don't wait!"
Want to see how the experts balance debt and retirement? Watch this guide to prepare for your future.
The road to financial freedom is not just about the big moves. It is about the hundreds of small, quiet decisions you make every single day. By balancing these two goals, you are building a resilient life. You are not just paying off the past; you are fueling your future. Stay the course and trust your plan.
Fine-Tuning Your Financial Engine
Once you have established the core of your wealth-building system, you might feel like you are on autopilot. That is a great place to be, but achieving true independence requires you to move from simply "doing" to "optimizing." Think of it like maintaining your car. You don't just change the oil once and assume the engine will run perfectly for decades without looking at the tires or the brakes.
The Debt Freedom Blueprint
- Momentum Matters: Choose the Snowball method if you need motivation.
- Math Wins: Choose the Avalanche method if you want to save on interest.
- Cash Flow: Make small, frequent payments to lower interest accumulation daily.
- Lifestyle Check: Don't let lifestyle creep undo your progress while you pay off debt.
Portfolio Rebalancing: Keeping Your Growth on Track
Most people assume that if they pick a good mix of stocks and bonds, they can leave it alone for a lifetime. That is a mistake. Over time, your high-performing assets will grow faster than your low-performing ones. If you started with a balance of seventy percent stocks and thirty percent bonds, a good year in the market might shift that to eighty percent stocks.
This means you are now taking more risk than you originally intended. Rebalancing is simply the act of selling a portion of your winning assets and buying the ones that are currently undervalued to get back to your target. It forces you to sell high and buy low, which is the most reliable way to manage risk. For a deep look at how markets behave over time, you can visit Investor.gov to see how asset allocation impacts long-term outcomes.
The Tax Strategy You Should Not Ignore
Many of us view taxes as just another bill to pay in the spring. I did too, for a long time. But the type of account you use matters just as much as the investment itself. You have tax-deferred accounts and tax-free accounts, and knowing how to leverage them is a secret weapon for your wallet.
If you are just putting money into a regular brokerage account, you are paying taxes on your dividends and capital gains every single year. By using accounts specifically designed for retirement or long-term growth, you can shield your money from that annual tax drag. This might seem small today, but over twenty years, the difference adds up to a massive amount. You can read more about how your investments are treated at the IRS Tax Topics page to understand the rules.
Locking Down Your Digital Fortress
In our modern world, your financial security isn't just about your bank balance; it is about your identity. I learned the hard way that one small security slip can wipe out years of hard work. You should practice the same caution with your financial accounts as you do with your physical wallet. Check out my guide on keeping your online bank accounts safe from hackers to see the simple steps you can take today.
The Automation Pro-Tip
You have automated your savings, but are you automating your credit score management? It is possible to turn your monthly bills into a higher credit score if you report them correctly. When you have a solid credit history, you get access to better interest rates, which saves you money every time you need to borrow for a big purchase. This is a pro-level secret that many beginners completely ignore.
Managing the Silent Thief
While you are focusing on growing your assets, you must account for the rise in the cost of living. If your money is sitting in a standard savings account, inflation is slowly eating away at your purchasing power. You can track current trends in the cost of goods through the Bureau of Labor Statistics to see how your money is losing value over time. You need your money to grow faster than the inflation rate, which is why investing is not just a hobby—it is a necessity.
Traps That Keep Professionals Stuck in a Rut
We all want to see our bank accounts grow, but sometimes our own behaviors hold us back. I see smart people making the same mistakes over and over because they believe they are "playing it safe." These habits might feel comfortable, but they are secretly costing you your future freedom.
The "I Deserve This" Spending Spree
Every time you get a small raise, do you immediately look for a way to upgrade your lifestyle? This is called lifestyle creep. It is the fastest way to stay broke forever. Even if you have made progress on your debt, don't celebrate by adding new recurring expenses.
Paying High Fees for "Average" Results
There are funds and advisors that promise to beat the market for you. They charge high management fees to do it. The problem is that study after study shows that these active funds rarely beat simple, low-cost index funds over the long run. You are paying them for the privilege of likely underperforming the market. Before you invest, always look at the expense ratio.
Falling for the "Get Rich Quick" Distraction
Every few months, someone will tell you about a new digital token or a hot stock that is supposedly going to the moon. They will show you screenshots of massive gains from their phone. It is very tempting to jump in. But remember, for every person who hits a jackpot, there are dozens who lost their hard-earned money. Treat your investment plan as a long-term journey, not a casino trip.
Ignoring the Fine Print in Mortgages
When you eventually buy a home, do not just look at the monthly payment. You need to look at the total cost of the loan. I have seen people jump into loans without decoding their mortgage disclosure forms first. If you ignore the closing costs and escrow requirements, you might find yourself with thousands of dollars in surprise expenses.
The Passive Income Fallacy
We hear a lot about "passive income" online. People claim you can just buy a course or an app and money will flow in while you sleep. The truth is, almost all passive income requires active work upfront. Falling for the passive income fallacy can lead you to spend money on schemes that don't pay off. If it sounds too easy, it usually is.
Neglecting the Emergency Buffer
I have met people who have a great investment portfolio but not a single dollar in an emergency fund. When their car breaks down, they have to sell their stocks at a loss to pay for repairs. That destroys their long-term growth plan. You must build a fail-safe emergency fund before you focus on aggressive market investments.
Building Your Own Success Story
Building wealth is not about being a genius. It is about being consistent. You do not need to predict where the stock market will be next week. You just need to show up and stay the course.
Action Plan for Tomorrow
- Check your allocation: Ensure your portfolio has not drifted away from your target goal.
- Audit your fees: Review your investment accounts and see if you are paying too much in expense ratios.
- Watch your score: Pull your report from AnnualCreditReport.com to make sure there are no errors hurting your potential.
- Review progress: Pick a date every three months to look at your "big picture" numbers, not just your daily spending.
I have found that the more I look at my money, the less anxious I feel about it. It stops being a monster under the bed and starts being a tool I control. I want you to feel that same sense of control. Start small, stay disciplined, and trust the process. You are doing this for the person you will be ten years from now, and that future version of you will be so thankful you started today.
My own journey started with a small, messy spreadsheet that I was almost afraid to open. But the day I decided to stop hiding from my numbers was the day my future changed. I took control, I made a plan, and I stuck to it. You have that same opportunity right now. Do not wait for the perfect moment. Take the first step and watch how your life begins to change.
Common Questions About Your Financial Future
Is it really possible to balance debt and investing?
Yes, it is possible. If your debt interest rate is low, you can often invest while paying off debt. It is about finding the right percentage of your income that goes toward each goal. You do not have to live on rice and beans if you manage your cash flow smartly.
How do I know if I'm diversified enough?
Diversification means owning a mix of different types of assets. If you own a total stock market index fund, you are already diversified across thousands of companies. You don't need to overcomplicate it by trying to pick individual stocks to feel "diversified."
What if I don't have much to start with?
Start with whatever you have, even if it is twenty dollars. The habit of saving and investing is more important than the amount you start with. As your income grows, your contributions will grow, but the habit is what creates the lasting change.
Should I worry about market drops?
Market drops are a normal part of the process. If you are investing for the long term, a market dip is actually an opportunity to buy assets at a lower price. If you want to invest wisely during market volatility, focus on your goals rather than the daily news.
Disclaimer: This content is for educational purposes only and does not constitute financial, legal, or tax advice. I am not a financial advisor. All financial decisions involve risk, and you should perform your own research or consult with a qualified professional before making any investment or loan choices based on your specific situation.